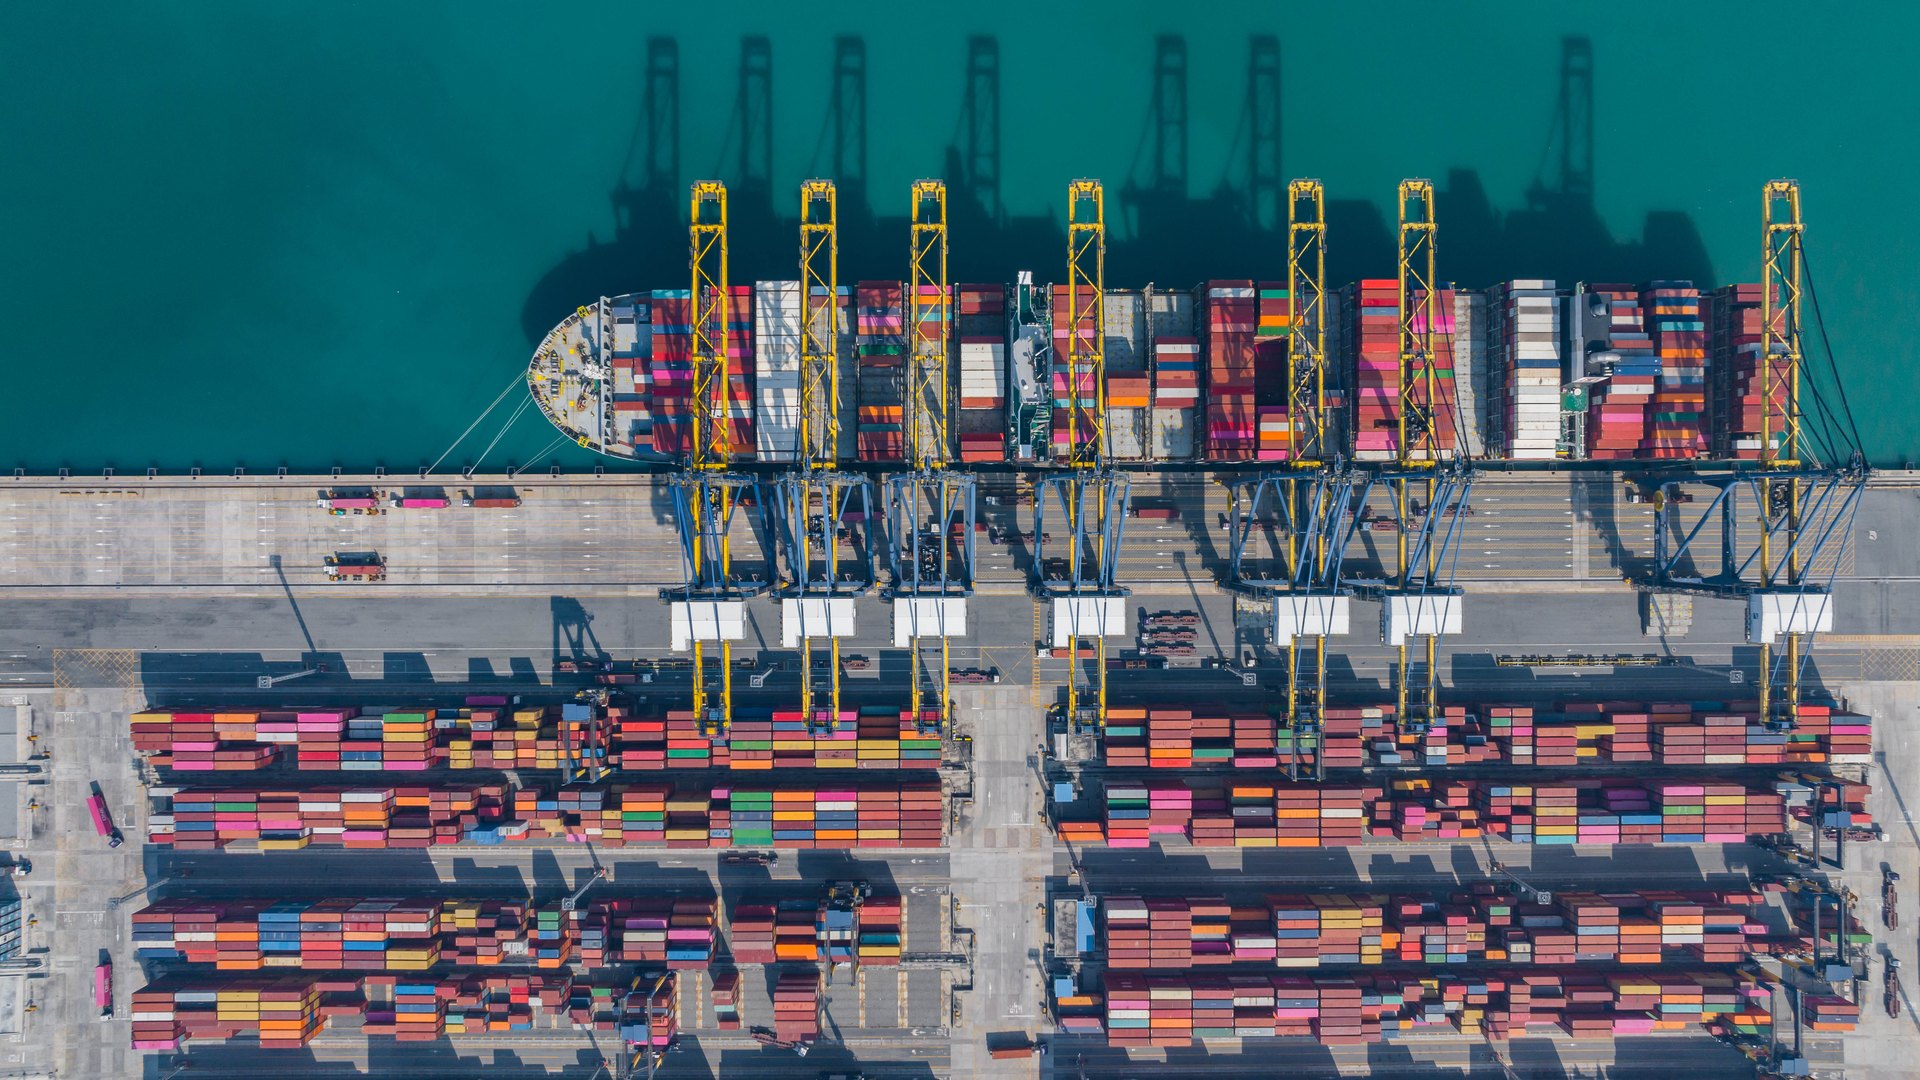
How physical disruption becomes a financing problem, and where cargo, war, trade disruption and parametric cover fit. Dalia De León Medina, Associate in our Cargo & Logistics team in London, explains.
Global supply chains have rarely been so exposed to disruption in the modern era. From the growing impact of climate change and extreme weather events to geopolitical tensions, war, sabotage, trade restrictions and infrastructure vulnerabilities, cargo owners face an increasingly complex and unpredictable risk environment. As supply chains become more interconnected, the consequences of disruption can extend far beyond the initial event, affecting the movement of goods, operational continuity and financial performance. In this environment, understanding and managing supply-chain risk has never been more important.
When logistics becomes a financing risk
For cargo owners, disruption and supply chain shifts are nothing new. What is changing is the speed with which a physical disruption can become a financing problem. For example, a vessel delayed at a strategic waterway does not simply arrive late. The associated inventory and product in transit remain financed for longer, credit lines stay utilised and interest continues to accrue.
At times, replacement cargo may need to be sourced at a different price while freight economics change, and contractual delivery obligations remain unless force majeure is declared and the whole contract is scuppered.
For the banks financing those flows, the same event can extend the cash-conversion cycle, delay repayment and alter the economics of the transaction being financed. This is why the distinction between damage to the cargo and damage to the trade is becoming increasingly important.
The distinction between damage to the cargo and damage to the trade is becoming increasingly important.
Hormuz: loss without damage
Allianz estimated that, in June 2026, around 1,150 cargo-carrying vessels were operating within Persian Gulf waters, representing approximately USD 125 billion in combined vessel and cargo value.
The significance of that figure is not simply the concentration of physical assets at risk. Much of the cargo may remain undamaged while being unable to move as originally intended. That distinction matters because traditional marine cargo insurance is primarily designed around physical loss or damage.
Delay, loss of market and frustration are excluded under a standard cargo policy, but coverage can be afforded elsewhere in the Trade Disruption Insurance (TDI) market, which has seen enquiries rise sharply in 2025 and 2026 and the entry of several new providers and managing general agents (MGAs) to meet client needs.
A delayed vessel can mean a missed contractual delivery window; a blocked route may require replacement material to be sourced at a higher differential; a diversion can generate additional freight, demurrage and financing costs.
The insurance cost itself can also alter the economics of the trade. Following the escalation around the Strait of Hormuz, industry participants reported significant increases in war-risk and cargo insurance costs, with total transit-related costs in some cases adding millions of dollars to individual voyages, according to Reuters.
Beyond crude: second-order effects
The Gulf matters far beyond crude oil: it is a critical source of petrochemicals, fertilisers and related feedstocks. United Nations Trade and Development (UNCTAD) has highlighted the exposure of global energy and fertiliser markets to disruption through the Strait of Hormuz, including the potential consequences for agricultural supply chains and food security.
The Middle East normally accounts for roughly one-third of global urea exports, and an estimated 2.6 million tonnes of exports were suspended in the first two months of the conflict, according to the Agricultural Market Information System (AMIS).
The disruption in the Strait of Hormuz has shown that interference in one maritime corridor can affect availability, replacement costs and production economics thousands of miles away.
Sulphur and sulphuric acid provide an example. Restrictions affecting Middle Eastern supply, together with trade measures elsewhere, can influence sulphuric-acid availability and ultimately the economics of copper production in markets such as Chile. The World Trade Organization (WTO) has tracked trade measures affecting commodities including urea, ammonia, sulphur and sulphuric acid in connection with disruption around Hormuz.
For a copper trader or miner, the relevant loss may therefore not be a damaged vessel in the Gulf. It may be the incremental cost of replacing a critical raw material elsewhere. That is both a supply-chain problem and a financing problem.
Rerouting can relocate risk
Alternative routes do not necessarily eliminate exposure; they can simply relocate it.
Saudi Aramco’s East-West pipeline, which runs 1,200 km across the Arabian Peninsula, provides an alternative to shipping via the Strait. Yet infrastructure disruption, sabotage attempts and the continuing security threat in the Red Sea demonstrate that the workaround itself can become vulnerable. In September 2026, Reuters reported that disruption affecting the Saudi East-West pipeline could threaten flows equivalent to approximately 4% of global oil supply if prolonged.
More recently, three pumping stations serving the pipeline were damaged in an attack and temporarily shut down. Consequently, route optionality needs to be assessed across the full transaction.
A change of port, vessel or jurisdiction can affect freight, war pricing, sanctions exposure, available insurance capacity and ultimately whether the trade remains commercially viable.
The question is no longer simply ‘Can the cargo move?’ but ‘Can it move legally, economically and within a structure that preserves the value of the transaction?’
Two conflicts, one insurance market
Continued attacks on vessels, ports and export infrastructure in the Black Sea have again demonstrated the vulnerability of a major corridor in global trade. In July 2026, traffic through Ukraine’s maritime corridor was suspended following increased attacks and fatalities among seafarers, The Maritime Executive reported.
For insurers, the Middle East and Black Sea are not entirely separate events. Both draw on the same global pool of Marine War capacity. London market estimates put Middle East Marine War losses in 2026 at between approximately USD 500 million and almost USD 1 billion, while total Marine War losses, including the Black Sea, had already exceeded USD 1 billion, according to The Insurer.
As losses accumulate, the market response may extend beyond price. Underwriters can reassess aggregates, vessel quality, geographical limits, deductibles and the amount of capacity they are prepared to deploy.
For commodity traders, access to a properly structured cargo war programme or binder can therefore provide greater certainty around physical war exposure as geopolitical conditions evolve.
But, once again, cargo war coverage addresses only one part of the problem: while a missile strike could well hit a cargo owner’s profit and loss (P&L), a vessel that remains intact but cannot deliver for three weeks is a separate exposure.
Trade disruption protection
The Baltimore Bridge disaster and the Panama Canal restrictions demonstrate why this issue extends well beyond armed conflict.
The collapse of the Francis Scott Key Bridge in Baltimore abruptly restricted access to a major US port. The event showed how damage to a single piece of infrastructure can affect cargo owners whose own goods remain undamaged and helped accelerate interest in specialist port-blockage and trade-disruption solutions.
Similarly, the Panama Canal, which handles around 5% of global maritime trade and roughly 40% of US container traffic, is again restricting traffic because of drought linked to El Niño. Under a draft plan, daily transits would average 29.5 vessels from October, 18% fewer than the 36 recorded in August.
With El Niño expected to peak later this year, and forecast to be the strongest in four decades, restrictions could tighten further, limiting transit capacity, lengthening waiting times and altering voyage economics. In September 2026, the Canal warned that insufficient rainfall could result in further restrictions, while its longer-term water-infrastructure solution remains several years away, according to Reuters.
The different causes of disruption produce a remarkably similar financial vocabulary: delay, additional freight, alternative routing, working capital, replacement supply and margin compression.
This is where TDI can become relevant. Depending on the wording, TDI can respond to defined financial consequences arising from events such as port closure, denial of access, government action, export restrictions or other specified disruptions, without requiring physical damage to the insured cargo.
The objective is not to transfer every adverse commercial outcome but to identify disruption risks that are material, definable and capable of being transferred rather than absorbed entirely within the cargo owner’s P&L.
Parametric solutions for cargo delays
Unlike traditional insurance products, parametric solutions offer a different approach: rather than beginning with the question ‘How much physical damage occurred?’, the cover begins with an objective and independently verifiable trigger. For instance, at Otonomi, a market leader in this product type, the loss trigger is linked to a shipment exceeding an agreed transit period by a specified number of days (effectively a time deductible), to another measurable logistics event, or to the shipment never arriving.
Once the threshold is reached, the policy responds according to the agreed payout structure, up to the limit purchased at inception (usually capped at around USD 500,000).
For commodity finance, the concept is particularly relevant because time is effectively one of the variables being financed in a trade. A bank advances capital against a transaction expected to monetise at a future date. If that date moves by two or three weeks, the physical cargo may be unchanged, but the economics of the financing are not.
A parametric solution can potentially convert part of that temporal uncertainty into predefined liquidity, acting as a hedge for the cargo owner. However, it does not replace cargo, cargo war or trade credit insurance; rather, it complements them, because its limits of liability are restricted, its cover does not extend to all conveyance types or to storage, and it carries war exclusions. Given how quickly parametric cover can move from quote to bind, we anticipate further growth and innovation in this product type in the short term.
From cargo to trade economics
Cargo owners are looking to build appropriate layers of protection around the transaction. Unfortunately, there is no ‘one-size-fits-all’ product capable of solving this problem. Instead, they tend to look at the following product suite, depending on their needs:
- Marine Cargo protects the physical commodity on an ‘all risks’ basis, excluding war and delay.
- Cargo War responds to insured physical war perils.
- Trade Credit protects accounts receivable from loss due to credit risks such as protracted default, insolvency or bankruptcy.
- Trade Disruption Insurance can address defined financial consequences when the supply chain fails without physical damage.
Traditional protections remain important as well. General Average is a reminder that an undamaged cargo can still generate a financial obligation following a maritime casualty, while Allianz continues to identify fire as a persistent source of serious container-shipping losses.
For cargo owners and their financing banks, the implication is broader than the design of any individual insurance policy. Commodity transactions already integrate price, freight, credit, liquidity and financing risk. Supply-chain disruption increasingly needs to be considered within that same framework.
Insurance cannot remove those risks, nor should it attempt to replace sound contractual, hedging or financing structures. Its role is to complement them by identifying exposures that can be transferred more efficiently, whether through conventional Marine Cargo, Cargo War, Trade Disruption or appropriately structured parametric solutions.
Insurance cannot remove those risks, nor should it attempt to replace sound contractual, hedging or financing structures.
For commodity markets, resilience will depend not simply on whether goods can be replaced after a loss, but on whether the financial structure of the trade can continue to perform when the physical supply chain does not.
When cargo stops moving, the real exposure may not be the commodity itself, but the economics of the trade built around it.
Talk to our Cargo team
Find out how we support cargo owners and commodity traders on our Cargo page.
ABOUT THE AUTHOR
Dalia De León Medina
Associate, Cargo & Logistics, London
Dalia places marine cargo, cargo war and stock throughput for commodity traders and cargo owners. She was previously a Fuel Oil Trader at PEMEX. ddeleonmedina@ogbroking.com
This is the cover story of Global View Edition II, Oneglobal’s magazine on the risks shaping global markets. Read the full edition or subscribe to Global View for free and get every edition straight to your inbox.